Portfolio construction
The 60/40 Didn't Fail. The 40 Did.
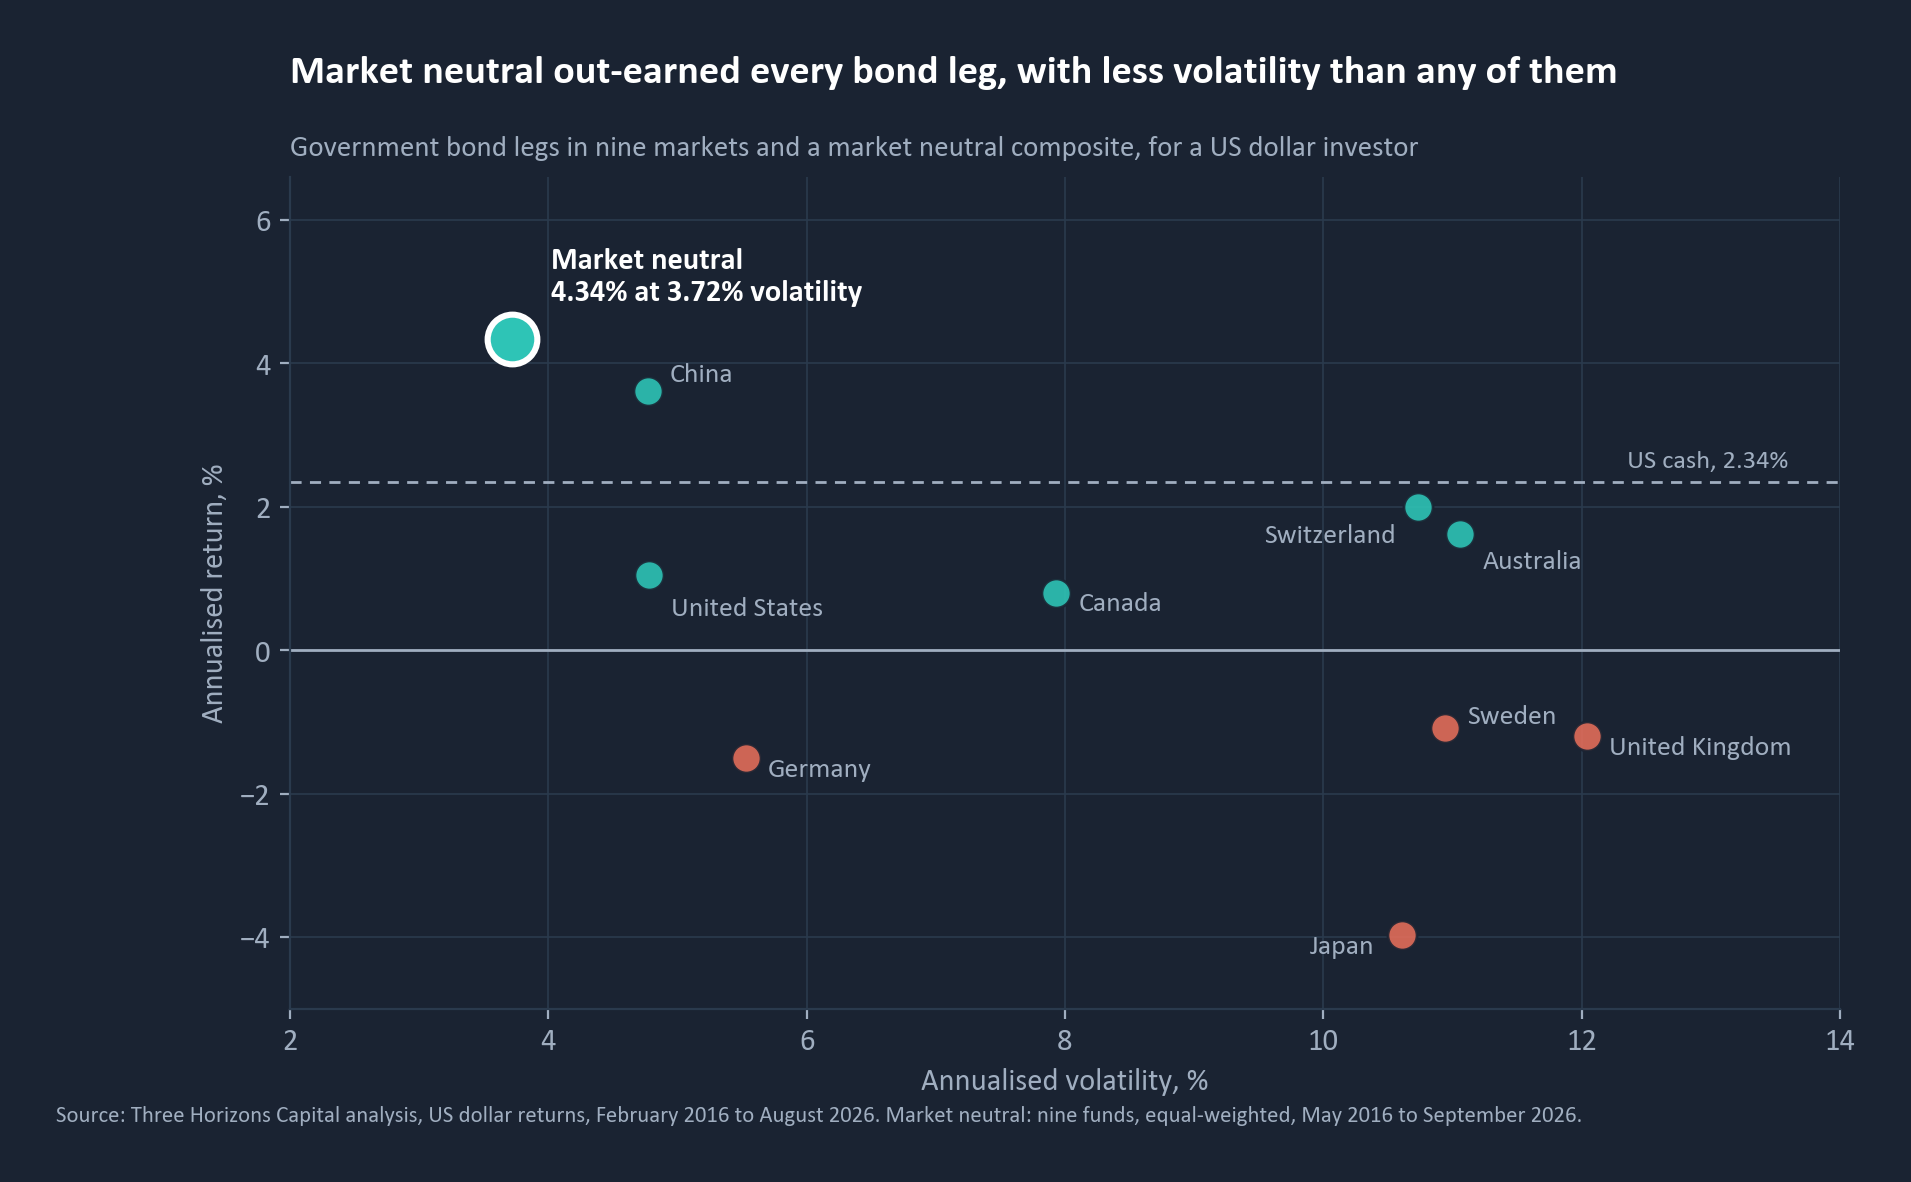
For a US dollar investor over the past decade, equities did their job in every market we tested. Government bonds earned less than cash in eight of nine. Replace them with market neutral and the 60/40 improved everywhere.
Three Horizons Capital, Portfolio Analytics. Monthly data, February 2016 to August 2026; market neutral composite May 2016 to September 2026. US dollars.
8 of 9
Government bond legs that earned less than US cash for a dollar investor, February 2016 to August 2026; four lost money outright
4.34% at 3.72% volatility
A market neutral composite's return and risk: a higher return than every government bond leg and lower volatility than any of them
+0.02 to +0.43
Rise in the 60/40's Sharpe ratio when market neutral replaced bonds, in all nine markets, from China to Japan
The finding in one line
For a dollar-based allocator, the decade's 60/40 problem sat in the bond leg: swapping government bonds for market neutral raised risk-adjusted returns in every market tested, at the cost of the deflationary-crash hedge this sample did not test.
The bond leg earned less than cash in eight of nine markets
We rebuilt the 60/40 in ten markets in US dollars. Against the 2.34% return on US three-month bills, eight of nine government bond legs had a negative Sharpe ratio, and Japan (−3.98% a year), Germany, the United Kingdom and Sweden lost money outright. Every equity leg earned a positive Sharpe ratio.
The bond leg set each 60/40's result
The United States had the best 60/40, a Sharpe ratio of 0.78. Japan shows the mechanism: equities returned 9.80% a year, but its 60/40 returned 4.35%, the lowest in the set, because its bonds lost 3.98% a year in dollars.
Swap the 40 for market neutral and every Sharpe ratio rises
A composite of nine market neutral funds returned 4.34% a year on 3.72% volatility. Used in place of each market's bonds, it moved every 60/40 to more return, less risk, or both.
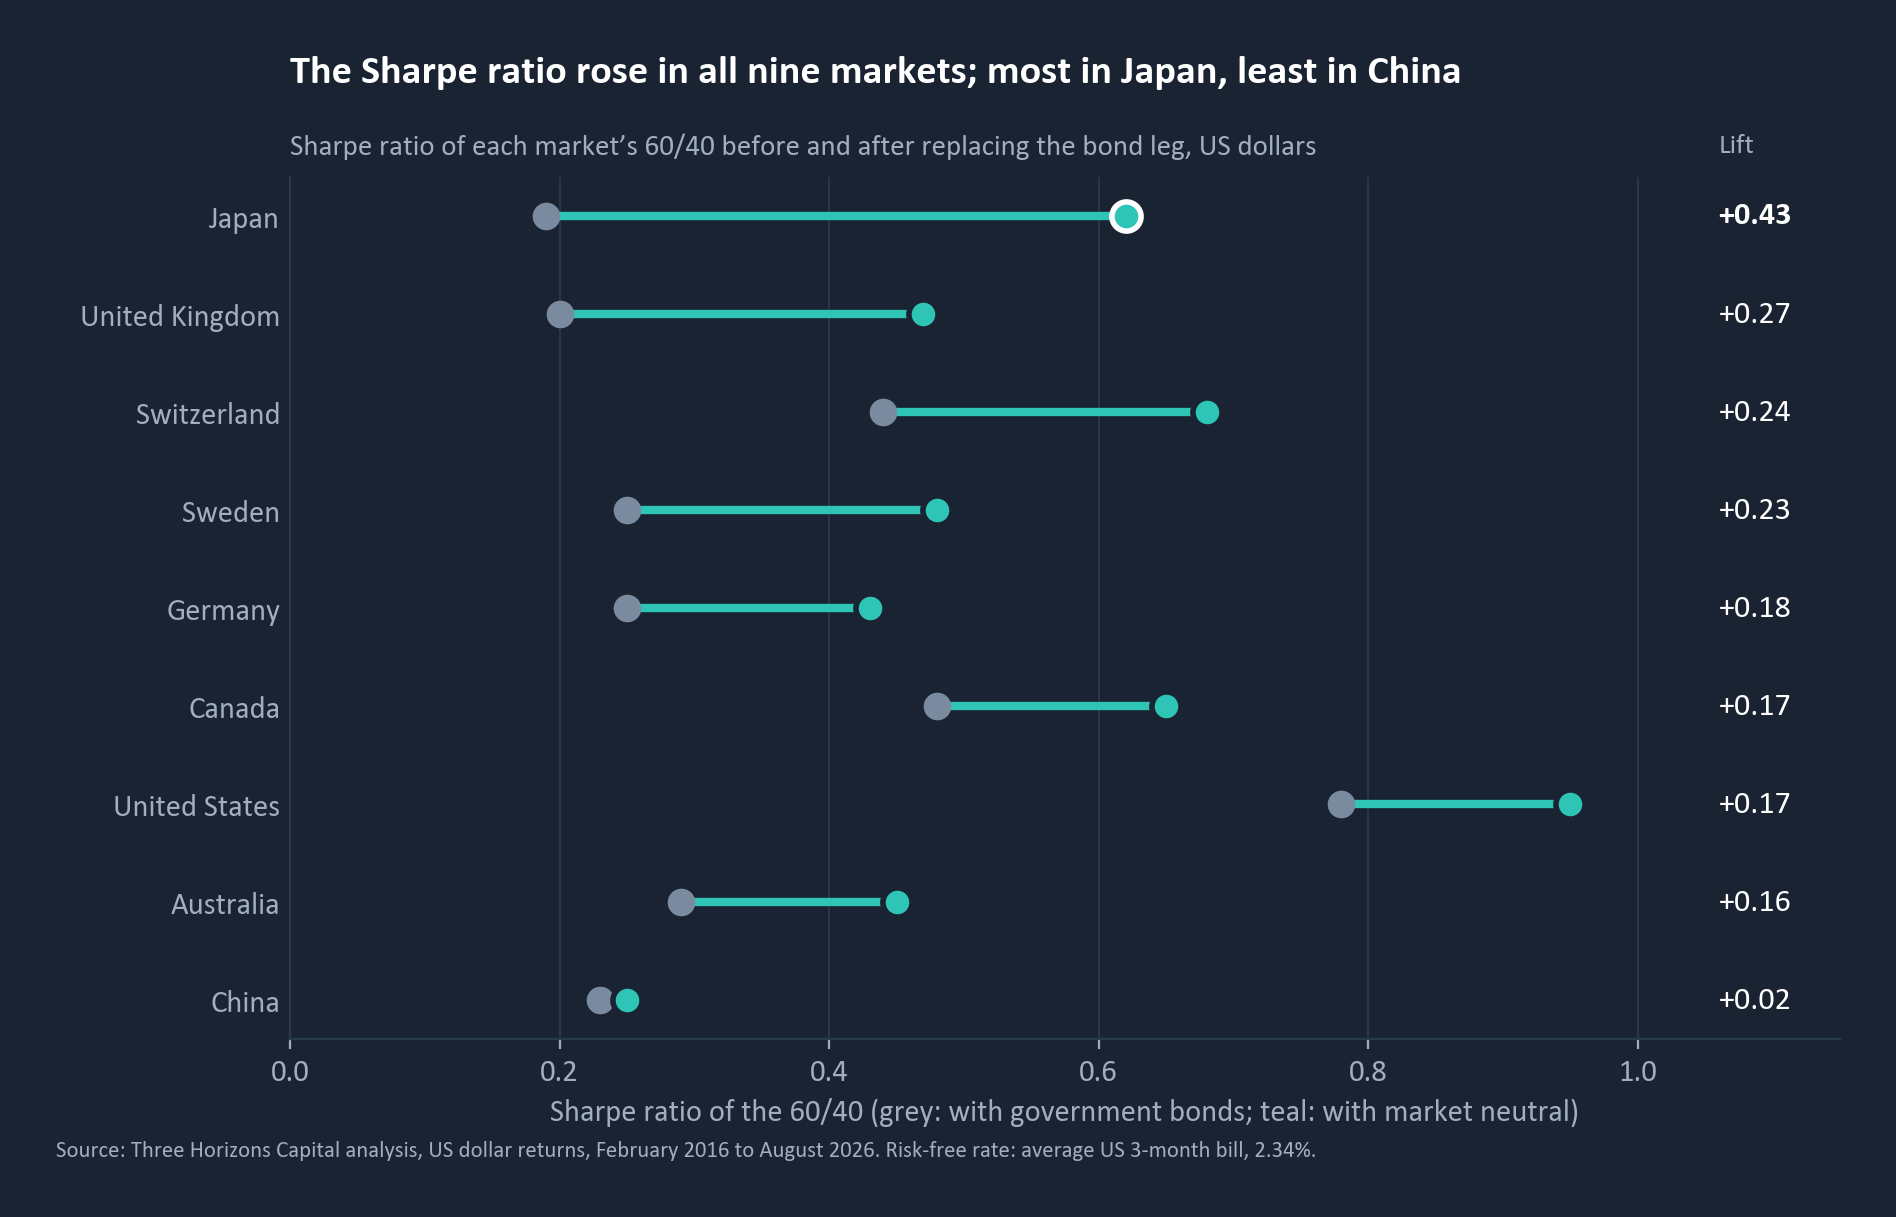
Japan gained most (+0.43), China least (+0.02). The United States stays first, at 0.95; Switzerland (0.68), Canada (0.65) and Japan (0.62) follow. France gets a full line for the first time, at 0.50.
What the swap gives up
The decade included the 2021 to 2023 rise in yields, a hard stretch for bonds. Government bonds earn their place in a deflationary crash, which this sample did not contain, and one global market neutral leg removes the cross-country rates diversification of the bond build. Read the full paper
So what for allocators
The question is not whether the 60/40 is dead. It is what the 40 is for: which job, in which crisis, in which currency.
Method: country equity and government bond total-return indices in US dollars, monthly rebalanced, February 2016 to August 2026; Germany's bond leg derived from 10-year Bund yields; market neutral = nine funds, equal-weighted, May 2016 to September 2026; Sharpe against a 2.34% US bill rate. No costs. A record of one decade, not a forecast. Prepared by Three Horizons Capital. Not investment advice.
If this is useful
We build this kind of look-through, across markets, currencies and sleeves, for portfolio teams deciding what each part of a portfolio is for. If that is the question in front of you, it is the work we do.