European fixed income
France Pays More Than Italy. This Is Not 2012.
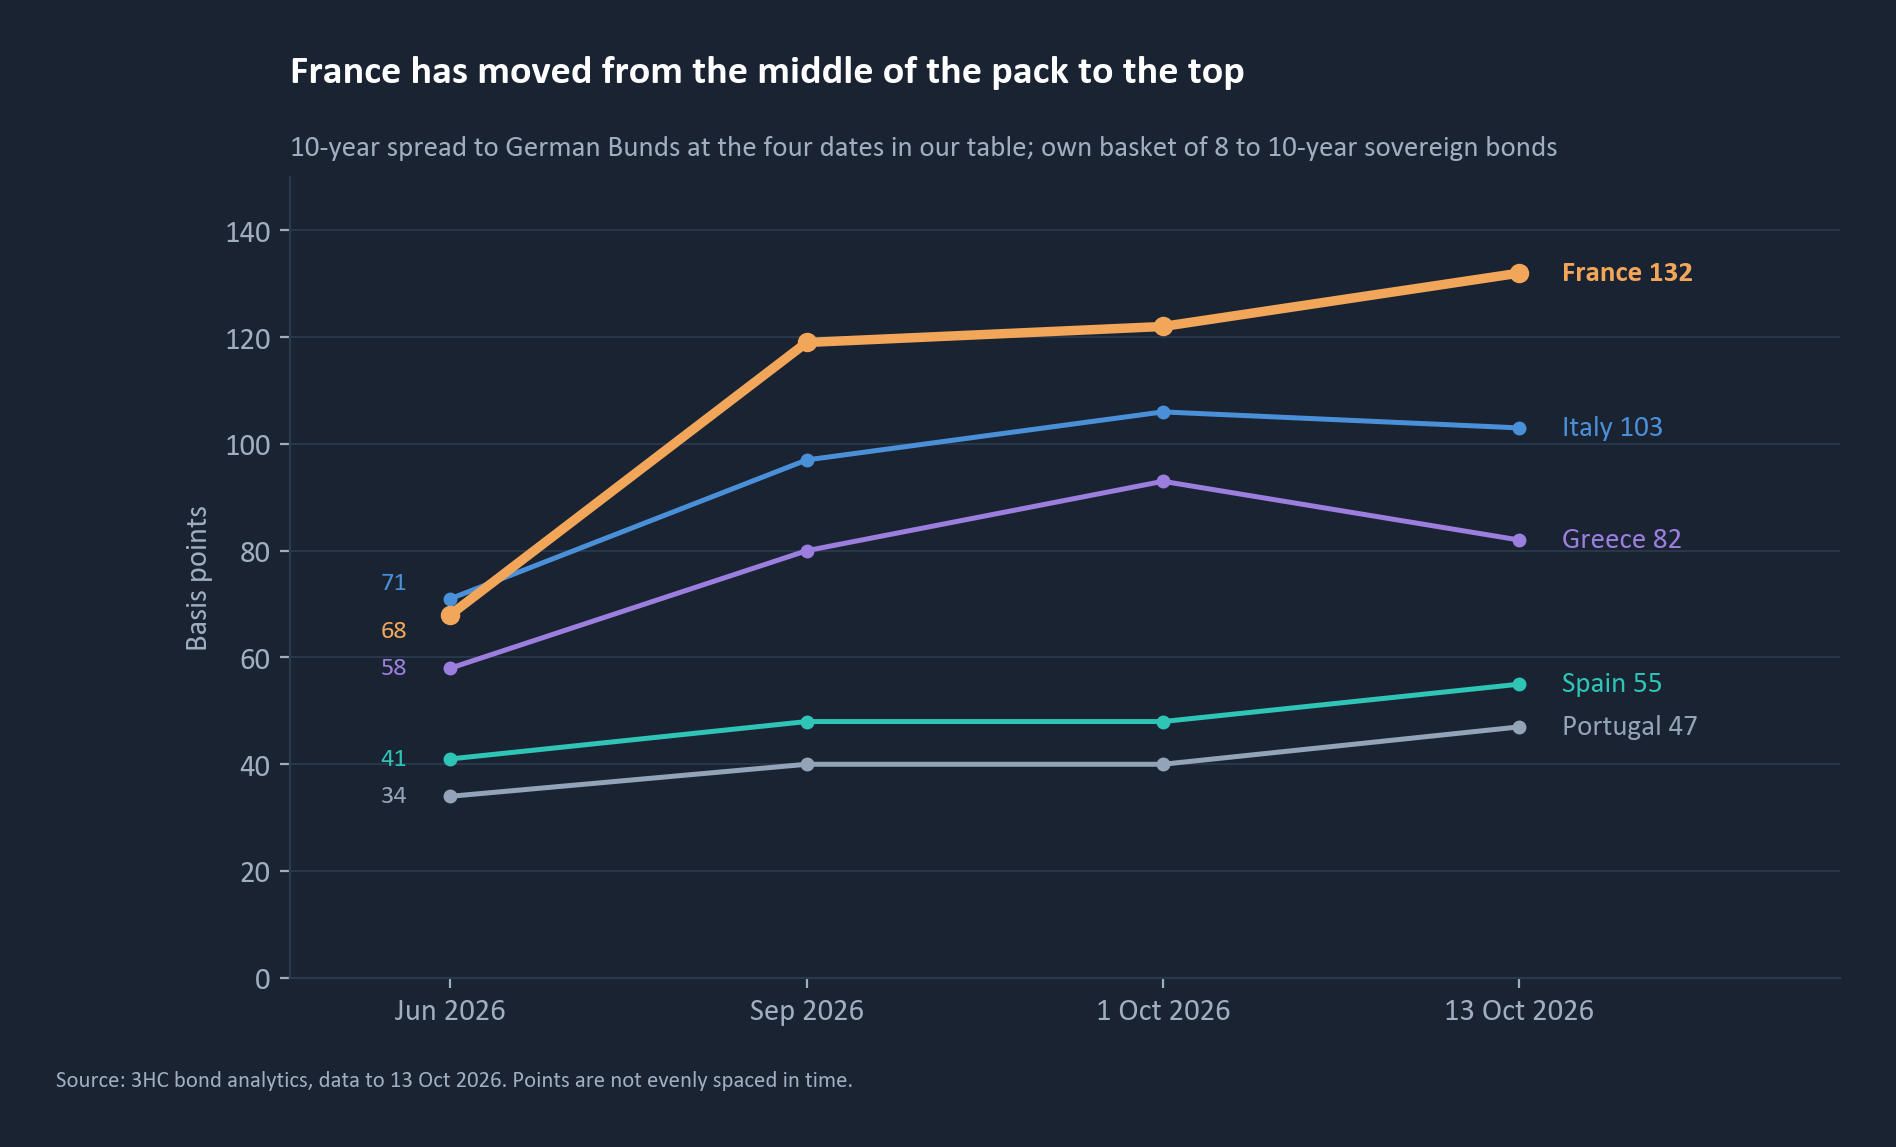
France's 10-year spread to German Bunds has risen from 68bps in June to 132bps, past Italy's. Our own read of five eurozone spread curves says this is a political repricing concentrated in France, on top of a shared European move, not the start of a sovereign debt crisis.
Three Horizons Capital, Portfolio Analytics. Sovereign spreads from 3HC bond analytics, own basket of 8 to 10-year bonds, to 13 October 2026; ETF flows to 8 October 2026.
132bps
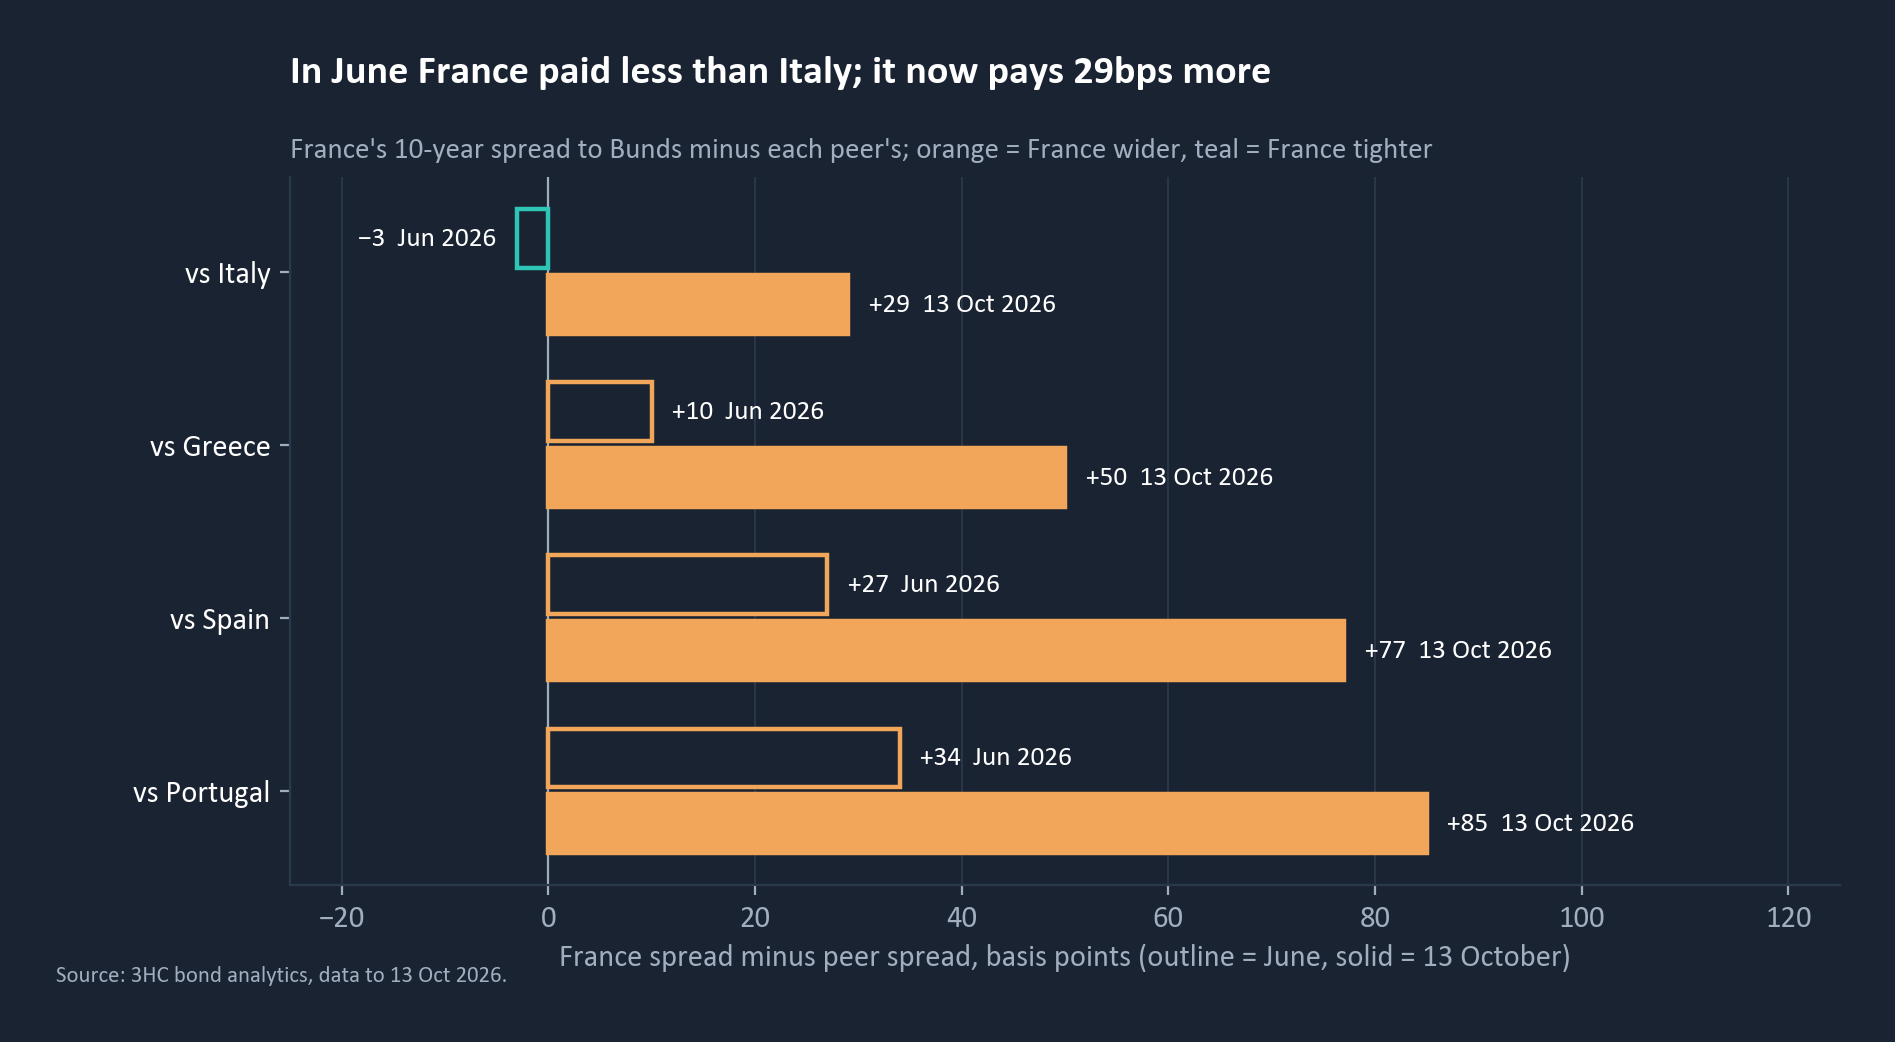
France's 10-year spread to Bunds on 13 October 2026, now 29bps above Italy and 50bps above Greece
About 3x
Rise in spread dispersion across five eurozone sovereigns since early 2026, concentrated in one name
+$715m
Net inflows to a broad euro-area government bond ETF from 1 April to 8 October 2026: no flight from European duration
The finding in one line
France is being repriced for its politics, not its solvency: part of the move is shared across Europe, the rest is France alone, and money is still flowing into euro government bonds.
France now pays more than Italy to borrow
In June, France's 10-year spread to German Bunds was 68bps, 3bps inside Italy's. By 13 October it was 132bps: 29bps above Italy, 50bps above Greece, and above Spain and Portugal too. A sovereign debt crisis widens the whole periphery together and keeps the ranking. Here one credit has jumped past peers whose fiscal paths are improving. That is the signature of a political repricing.
Two moves, not one
Month-to-month changes in France's spread correlate at 0.71 to 0.87 with Italy, Spain, Greece and Portugal, and a majority of its widening, roughly 50% to 70% depending on specification, moved with the rest of Europe: a shared duration sell-off. The France-only part turns positive from September 2026, in step with the budget and parliamentary calendar, not with any funding-stress data. Meanwhile dispersion across the five has roughly tripled, from about 12bps to 13bps to about 33bps to 36bps, because one name moved away from the rest.
Money did not run
A broad euro-area government bond ETF of about $6bn took in +$715m of net inflows from 1 April to 8 October 2026, right through the French stress. One fund is not the whole market, but a crisis shows up in flows first, and these point to repricing, not flight.
Our view
A political repricing, not a solvency event, and one to treat as a feature of the next 12 to 18 months rather than a spike to fade. We expect the France-specific premium to stay elevated and choppy around budget votes and confidence motions. We would not price Italy, Spain, Greece or Portugal off France. We stay neutral on aggregate euro-area duration and prefer credits whose improving rank order is intact over France.
- Treat France as single-name risk within sovereigns and size it on its own.
- Do not price the periphery off France.
- Separate the shared duration move from the France premium; they need different hedges.
- Watch dispersion, not just levels, in sovereigns, equity and credit.
What would change our mind: the periphery re-widening in lockstep with France, rating trajectories reversing in the periphery, sustained outflows from euro government bond funds, or ECB action on Transmission Protection Instrument eligibility for France.
Read the full paper for the decomposition, the dispersion and flow evidence, the debt arithmetic, our currency and equity view and the method.
Method in the full paper: own basket of 8 to 10-year sovereign bonds (3HC bond analytics); one broad euro-area government bond ETF as the flow proxy. Research, not investment advice.